Trump Media Races to Clear Rp14.7 Trillion Bitcoin Debt Before November 30 Deadline
Baca dalam 60 detik
- Trump Media & Technology Group berupaya melunasi utang obligasi konversi senilai USD883,5 juta yang dijamin bitcoin tanpa harus melepas aset kripto tersebut.
- Perusahaan mengandalkan kas dan fasilitas kredit baru, sementara opsi konversi saham tidak menarik karena harga saham anjlok ke sekitar USD4 dari harga konversi USD34,72.
- Jika gagal, Trump Media terancam menjual cadangan bitcoinnya yang nilainya telah menyusut sekitar USD312 juta sejak akhir September 2026.

Trump Media & Technology Group (DJT) faces its most critical financial test since the company placed bitcoin at the heart of its treasury strategy. In less than two weeks, on November 30, 2026, holders of convertible bonds totaling USD883.5 million will be entitled to demand full cash payment. The company, whose majority shares are controlled by President Donald Trump's trust, is now racing against time to clean up its capital structure without having to offload the bitcoin reserves that have been the mainstay of its returns.
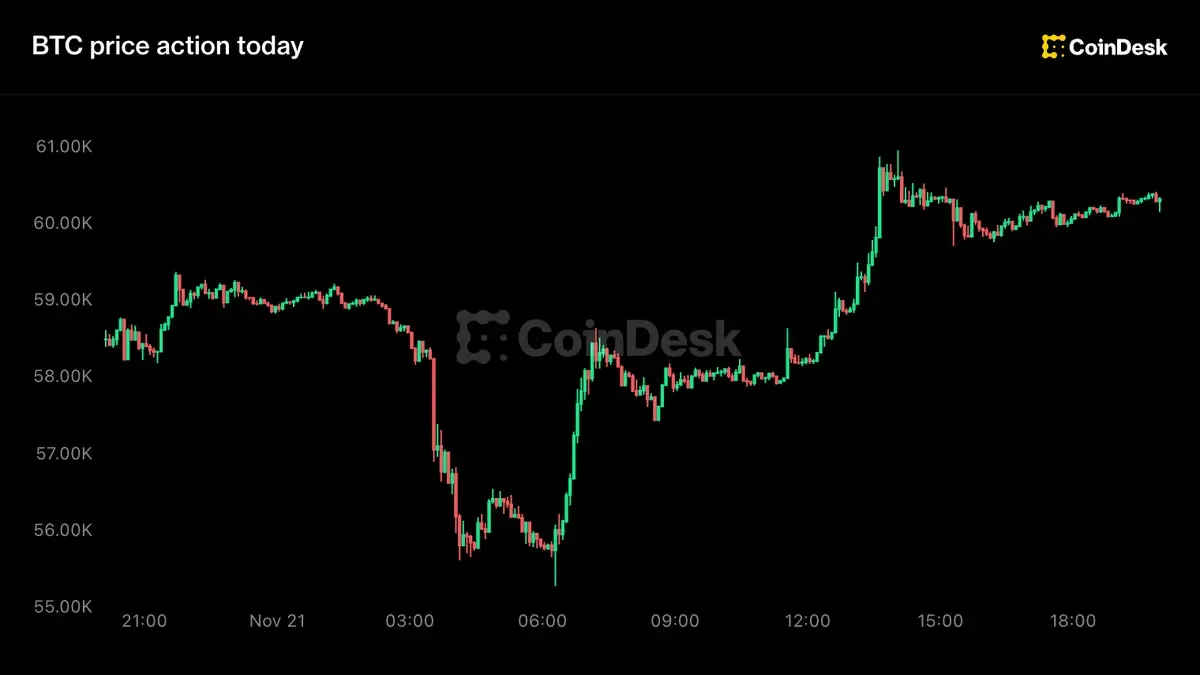
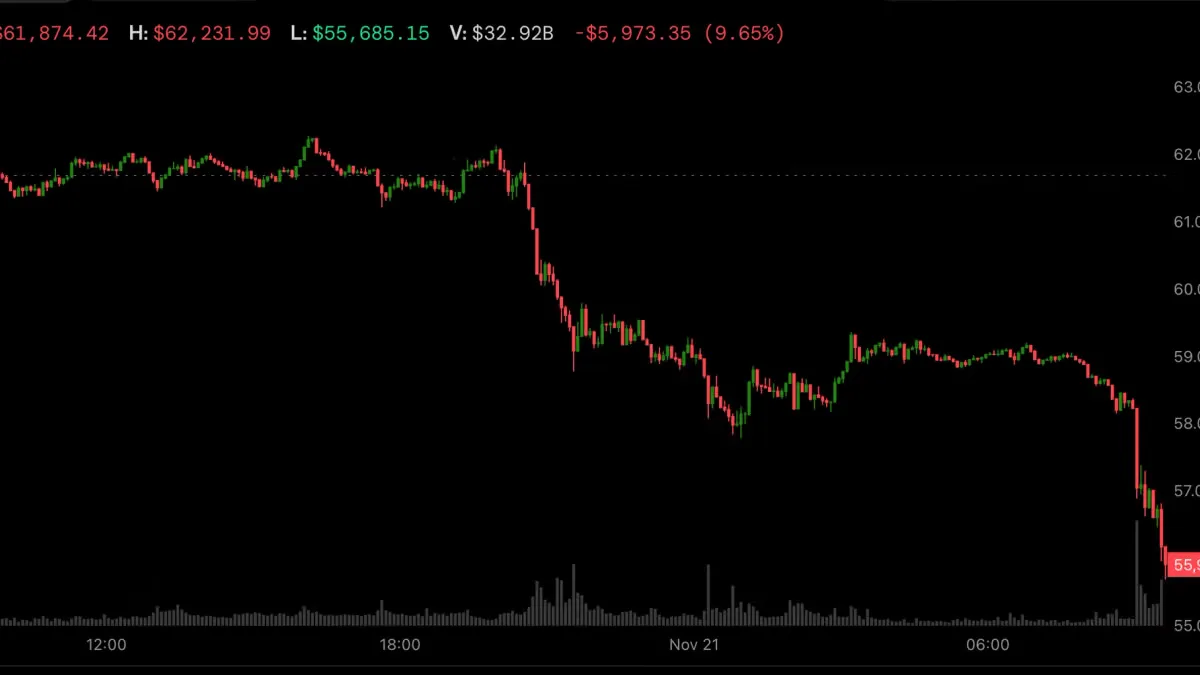
The problem is not just the amount. Since issuing USD1 billion in zero-interest bonds in May 2025 to finance bitcoin accumulation, the digital asset market landscape has changed drastically. The bitcoin price on Thursday afternoon was around USD63,750, far below the level that made the company's yield strategy look promising. With 15,649 BTC held as of September 30, the value of Trump Media's reserves is now about USD998 million, down from about USD1.31 billion at the end of the third quarter. The decline in the value of the collateral assets narrows the company's room to maneuver.
The first step has been taken. Trump Media announced the repurchase of USD100 million of bonds last Tuesday at below par value, using available cash. The remaining obligation is about USD883.5 million. Interim CEO Kevin McGurn stressed that the company intends to use existing cash and credit to tidy up its capital structure, without issuing new equity. That statement was reinforced in the November 9 earnings call, when McGurn said he wanted to retain as much bitcoin as possible so the yield strategy could continue and the asset could recover.
The option to convert into shares is practically irrational for bondholders. With a conversion price of USD34.72 and the stock having slumped to around USD4, choosing equity means accepting a large loss. That is why the pressure to pay cash is growing. But the company's cash is not plentiful. Besides spending funds on the buyback, Trump Media has also spent cash on a planned merger with TAE Technologies and drew a new USD100 million loan in early October. The company's quarterly report even warned that if other funding sources are insufficient, they may have to sell bitcoin or other digital assets to finance the repurchase.
"We want to retain as much of our bitcoin as possible to continue the yield strategy and let that asset recover," said Kevin McGurn, interim CEO of Trump Media, in the November 9, 2026 earnings call.
On-chain traces add another dimension. Analysis by the Arkham platform recorded about 4,259 BTC moving on November 5 from a wallet labeled as bond collateral to an address linked to Crypto.com. The transfer does not necessarily indicate a sale, but it triggered speculation that the company is preparing liquidity or restructuring collateral. Trump Media has not responded to a request for confirmation from CoinDesk.
For the global crypto market, this case is a stress test of the aggressive corporate treasury model. Companies that place bitcoin as a debt collateral asset now face the reality that price volatility can trigger cash obligations sooner than expected. In Indonesia, the Financial Services Authority (OJK) and Bank Indonesia have tightened supervision of crypto asset exposure on corporate balance sheets, including through valuation and risk disclosure rules. Although Trump Media is not a domestic entity, turmoil triggered by crypto-based debt obligations could affect Indonesian retail investor sentiment toward digital asset-related investment products, especially ahead of the implementation of a stricter crypto asset regulatory framework in 2027.
The most closely watched issue is the Trump trust's position. With 114.75 million shares, or about 41% ownership, the value of that stake has eroded to about USD460 million at USD4 per share. Issuing new shares to pay off debt would dilute that ownership, something undesirable both politically and financially. But selling bitcoin amid a price that has fallen by nearly a quarter from its end-September value also means realizing a loss. The remaining options are negotiation with bondholders, seeking new credit, or a combination of both.
The market will watch whether Trump Media can get past November 30 without a massive bitcoin sale. If it succeeds, the company proves that a crypto-based treasury structure can survive a downturn. If it fails, selling pressure from one of the largest corporate bitcoin holders in the United States could set a bad precedent for other issuers that copy the same strategy. The question now is simple: how long can bitcoin reserves be held as collateral without becoming a burden?